Suzlon Energy’s Q2 FY27 Earnings: Beyond the Headlines
If you only looked at financial news tickers right after Suzlon Energy dropped its Q2 FY27 numbers, you would have seen some pretty jarring alerts: “Suzlon Energy Net Profit Plunges 69% YoY.” Naturally, short-term traders panicked. But if you dig beneath the surface of the financial statements, this is actually a classic case where base-effect distortions completely hide the true health of the business.
| Metric | Q2 FY27 Value | Comparison / Growth |
| Consolidated Revenue | ₹4,869.05 crore | 26% increase YoY (vs. ₹3,865.54 crore); 27.5% jump QoQ (vs. ₹3,819.36 crore) |
| Wind Turbine Deliveries | 710 MW | 40% increase from Q1; 26% higher YoY |
| Project Commissioning | 454 MW | Up 69% sequentially; nearly 196% higher YoY |
| Consolidated EBITDA | ~₹720 crore | Essentially flat compared to ₹721 crore in Q2 FY26 |
| EBITDA Margins | 14.8% | Contracted by ~386 basis points YoY (vs. 18.6% in Q2 FY26) |
| Net Worth | ₹10,277 crore | Crossed the ₹10,000 crore threshold |
| Net Cash Position | >₹2,048 crore | Supported credit rating upgrades by CRISIL (AA-/Stable long-term, A1+ short-term) |
| Order Book | >6 GW | Provides roughly 18 months of clear revenue visibility, skewed toward PSUs and C&I clients |
Once you strip out the non-recurring accounting anomalies, the real story looks completely different: Suzlon is seeing strong operational growth and record-breaking project execution, even if it’s currently dealing with some margin headwinds.
1. The Reality Behind the “69% Profit Drop”
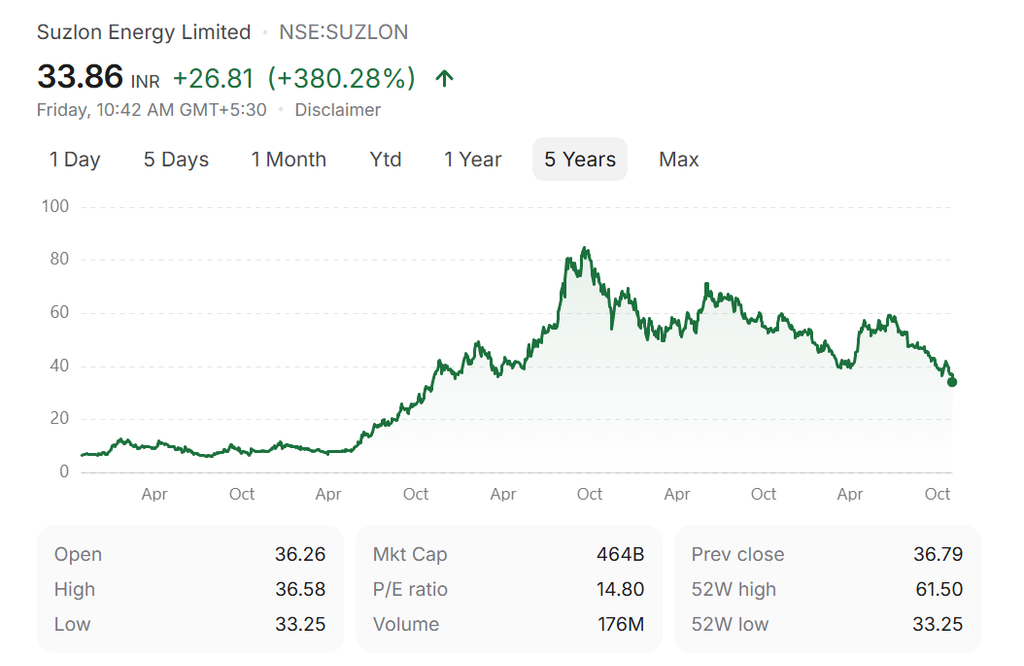
On paper, the consolidated net profit (Profit After Tax, or PAT) landed at ₹394.15 crore. Compared to the ₹1,279.44 crore reported back in Q2 FY26, that looks like a steep 69.2% drop.
Here’s why that number is misleading: Q2 FY26 included a massive, one-time deferred tax asset creation of ₹891 crore, which made the previous year’s base profit look artificially huge.
When you normalize things by taking out that exceptional tax credit, Suzlon’s core underlying net profit actually grew 1.3% year-on-year. Looking at it quarter-on-quarter, the momentum is even clearer—net profit jumped 29.1% compared to Q1 FY27’s ₹305.22 crore.
2. Top-Line Growth and Execution Speed
While everyone was busy talking about the headline profit numbers, the real takeaway this quarter is how fast the company is executing and scaling up.
- Surging Revenue: Consolidated revenue from operations climbed to ₹4,869.05 crore, marking a solid 26% bump YoY (up from ₹3,865.54 crore) and a 27.5% jump QoQ (up from ₹3,819.36 crore).
- Faster Deliveries: Suzlon shipped out 710 MW of wind turbines in Q2 FY27—a 40% increase from Q1 and 26% higher than the same time last year.
- A Big Jump in Commissioning: Project completions accelerated sharply, with commissioning reaching 454 MW. That’s up 69% sequentially and nearly 196% YoY.
This kind of operational spike proves that Suzlon is successfully pushing through monsoon-season hurdles and turning its massive order backlog into actual ground-level progress.
3. Where the Margin Pressure is Coming From
Even with soaring revenues and deliveries, consolidated EBITDA stayed flat at around ₹720 crore (compared to ₹721 crore in Q2 FY26).
Because the top line grew faster than operating earnings, EBITDA margins dipped by about 386 basis points down to 14.8% (from 18.6% a year ago).
A few things are driving this margin pinch:
- Scope and Customer Mix: They are handling a higher proportion of Engineering, Procurement, and Construction (EPC) work compared to just supplying equipment, which changes the margin profile.
- Cost Volatility: Ongoing commodity price fluctuations and foreign exchange friction added some extra weight to input costs.
- Strategic Investments: The company absorbed roughly ₹50 crore in non-recurring expenses for internal scaling and structural upgrades (like their Suzlon 2.0 initiatives).
4. Balance Sheet Health and Corporate Updates
Looking past the profit-and-loss statement, Suzlon’s financial foundation has gotten noticeably stronger:
- Net Worth Milestone: Consolidated net worth officially crossed the ₹10,000 crore mark, sitting comfortably at ₹10,277 crore.
- Credit Upgrades: Backed by a healthy net cash cushion of over ₹2,048 crore, CRISIL bumped Suzlon’s long-term credit rating up to AA-/Stable and its short-term rating to A1+, showing how far the company has come from its past struggles.
- Housekeeping Moves: The board approved acquiring 100% equity in Suzlon Foundation Limited for ₹10 lakh to bring their CSR efforts under one roof, alongside investments to secure their corporate headquarters (the One Earth premises) through OE Business Park Private Limited.
5. Analyst Outlook and What’s Next
With an order book sitting firmly above 6 GW—skewed mostly toward PSUs and Commercial & Industrial (C&I) clients—Suzlon currently has about 18 months of clear revenue visibility locked in.
The Bottom Line: Suzlon’s Q2 FY27 report is a classic split narrative. On one side, execution speed is firing on all cylinders, riding the wave of India’s massive push toward renewable energy. On the other side, they are feeling the pinch on operating margins. For long-term investors, the big thing to watch isn’t headline profit noise; it’s whether management can protect those operating margins while working through a multi-gigawatt order book.
Suzlon Energy, Suzlon Energy Q2 FY27, Suzlon Energy earnings, Renewable energy India, Wind turbine deliveries, Consolidated revenue, EBITDA margins, Deferred tax asset, CRISIL credit rating upgrade, Wind energy sector India, #SuzlonEnergy, #StockMarket, #Q2FY27, #GreenEnergy, #RenewableEnergy, #WindPower, #IndianEconomy, #StockAnalysis